Calculating Net ProfitFor Texas owners holding a figure.
The practice keeps its work in Dallas, and the video call is where a Texas owner names the figure.
Name the Texas figure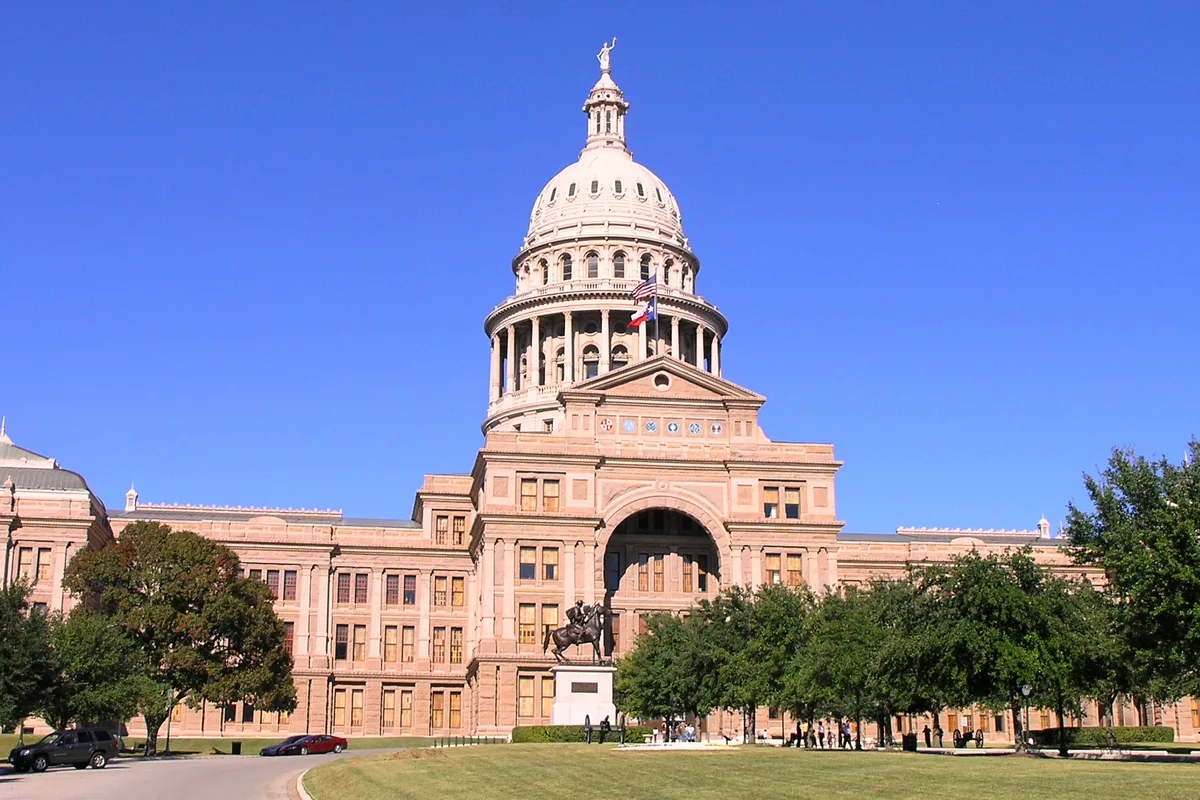
A fourth label beside the three you already have.
Show the next lines
Someone reading from the Hill Country, from the Gulf shore, or from the Panhandle is outside both Dallas and Fort Worth, and the only local claim on the video call is that the people talking are Texans together. The month stays on the screen already open in front of you. Nobody travels to a room for the naming of the figure.
The picture is the Texas State Capitol in Austin, from the front lawn at an angle. Daniel Mayer made the photograph. Wikimedia Commons holds the file under CC BY-SA 3.0. The practice meets no one under that dome.
The software row, the tax figure, and the cash change are the three labels on every other page here. Texas adds a fourth label for a company that has to file a franchise report. That fourth label can be zero and the report can still be waiting. A zero tax with a missing report is how a clean software row still gets stuck.
We read the closed month you already finished. The May report uses numbers that start from the federal return, so an open month under the software row will move the Texas starting number. The figure they asked for does not leave while that month can still change.
Who has to file the May report.
Show the next lines
The franchise report is the privilege tax a company pays for the right to exist in Texas, and publication 98-806 is where the Comptroller lists the filers. Corporations are on that list, and so are banks, S corporations, partnerships, trusts, professional associations, and joint ventures. A limited liability company is on it as well, including the one-owner company and the series company, which matters here because the software row looks the same in all of those files.
A person who never formed a company, and who only has a software row in their own name, generally stays off the May list. A general partnership made up only of natural persons generally stays off too, until that partnership becomes a limited liability partnership, which is the split in Rule 3.586. We ask which shape is real before anyone calls the May page optional.
Some files can skip both short forms, and we treat the skip as a fact to confirm rather than a hope. The skip covers an exempt organization, a company with neither a Texas charter nor Texas nexus, a passive entity, and a qualifying new veteran-owned business during its first five years. A guessed skip is how the letter shows up later.
Inside a combined group the margin method is chosen once for the group. Any member organized in Texas, and any member with nexus, still sends its own short report, and that member does not get to pick a second method just because its software row looks different.
15 May sits beside the federal figure.
Show the next lines
A calendar-year S corporation or partnership has a federal figure that clusters near the middle of March. The Texas franchise report lands on 15 May next to that figure, and the two dates belong to two different readers. Finishing the federal figure leaves the May page untouched.
If 15 May lands on a weekend or a holiday, the Comptroller's calendar pushes the report to the following business day, and we check that year's shift on the extensions page rather than remembering it. This page leaves the shifted day off on purpose, because a remembered shift is how the wrong day gets written into the letter.
The software row that closed during the 2024 report year, and the one that closed during the 2025 report year, may use a pay cap of 450,000 dollars and may treat revenue at or under 2,470,000 dollars as the point where franchise tax falls to zero, and neither of those two amounts may be copied onto a software row from a later close. The software row from a 2026 close, and the one from a 2027 close, moves that zero-tax point up to 2,650,000 dollars, and handing a lender the higher point while the file in front of you is the older close is handing over the wrong figure.
Even under the no-tax-due threshold, the company still files Form 05-102, the public information report, or Form 05-167, the ownership information report, unless it sits on the skip list above. A threshold that removes the tax does not remove the report.
Four ways to compute the margin.
Show the next lines
The company picks one of four margin paths, and we write that pick down beside the label a stranger already asked for. The paths are seventy percent of total revenue, revenue after cost of goods, revenue after compensation, and revenue after a 1,000,000 dollar floor that opened on 1 January 2014.
Total revenue starts from the federal amounts and then subtracts the exclusions in Tax Code section 171.1011. An open month under the federal figure moves that starting number. We will not name the margin while the month is still moving.
Cost of goods generally covers tangible personal property and real property. A service company often has no cost of goods under section 171.1012. Calling every expense a cost of goods is the mistake that makes the margin look smaller than the statute allows.
For reports due in 2026 and 2027, retail and wholesale entities use 0.375 percent and other entities use 0.75 percent. The compensation cap in those years is 480,000 dollars. The EZ computation, at 0.331 percent, is available at 20 million dollars of revenue or less. Those rates belong to those years. They do not get copied onto a 2024 report.
What compensation includes.
Show the next lines
On the compensation path, the amount that counts is W-2 pay plus cash to officers, directors, owners, partners, and employees, and that cash includes net distributive income to a natural person, stopped at the per-person cap, with the benefits the statute counts added on, while 1099 labor and the employer's own payroll taxes stay outside that amount.
That split is the same kind of split we already make on a loan draft. One amount leaves the bank. Only part of the amount belongs in the figure the form is allowed to use. The rest stays in a different label.
After the path is chosen, gross receipts decide how much of the margin is Texas, and a company selling into several states keeps the other states' receipts off the Texas share. We name that receipts line before anyone treats the margin as the figure a lender can have.
A new officer waits for the next annual report unless an amended report is filed. Moving the registered agent is a Secretary of State filing of its own, and Forms 05-102 and 05-167 are the wrong place to park that change.
When the report or the tax is late.
Show the next lines
Before that figure goes out, know the late charges that can sit on top of it, which are a 50 dollar charge when the information report itself is late, an added 5 percent when the tax arrives inside the first month, an added 10 percent when the tax arrives later than that, and interest that begins on day 61, with the percent left on the Comptroller page instead of copied onto this one.
An extension generally needs 100 percent of the prior-year tax, or 90 percent of the current-year tax. A company in its first year of being subject to the tax cannot use the 100 percent path. The first year has no prior-year tax to copy.
Extension timing depends on how the company pays. A filer who is off electronic funds transfer can push the report through Webfile or Form 05-164 as far as 15 November. Once tax has reached 10,000 dollars, an electronic filer gets 15 August first and 15 November after that. At 500,000 dollars the money moves on TEXNET under code 13080 and Form 05-164 stays unsent. Check the live extensions page for the TEXNET hour before you trust a memory of it.
The forfeiture provisions a company can trip are Tax Code sections 171.251, 171.2515, 171.252, and 171.255, and sections 171.259 and 171.260 keep those provisions from reaching financial institutions. Losing the right to transact in Texas is a separate problem from a mislabeled software row, so we give it a separate name.
A research and development credit was rewritten for any filing dated 1 January 2026 or later, and this page refuses to compress that rewrite. Read the Comptroller's credit page before a credit is placed on the report.
When the company leaves Texas.
Show the next lines
A final report is due within 60 days after Texas nexus ends, and the company can receive an extra 45 days. Leaving the state does not erase the last report. The software row for that last period still has to be a closed period before the final margin is named.
A company that keeps selling into Texas after the office closes may still have nexus. We ask what still touches Texas before anyone treats the final report as the last page.
Sales tax is a different figure.
Show the next lines
Sales tax sits apart from the franchise margin and apart from the software row. The state piece is 6.25 percent, localities may add no more than 2 percent, and the two together stop at 8.25 percent. No city rate is printed here, because a city rate moves and a remembered one is how the wrong amount gets collected.
Collection timing is its own label. Monthly sellers file on the twentieth of the month after the sales, and the Comptroller's worked example is April's sales due on 20 May. Sellers on a quarter use the windows that open in April, July, October, and January. A seller the Comptroller has placed on the yearly rhythm sends that one sales report on the twentieth day of January, after the whole prior year of tickets has a name on the software row.
A timely filer may take a discount of five tenths of one percent. A prepayment adds 1.25 percent on top of that treatment. The return is Form 01-339. Keep the records four years.
A sales payment over 1,000,000 dollars has to be started on TEXNET by eight in the evening, Central Time, on the banking day before the due date. A payment of 1,000,000 dollars or less may run until ten in the morning, Central Time, on the due date itself. We read that clock on the live page when the payment is close.
A marketplace seller and the safe harbor.
Show the next lines
Marketplace sales count in total Texas sales. They come out of taxable sales when the provider's terms say the provider will collect. The word on the provider's own terms is the word we use. A remembered promise is not the paper.
A remote seller under 500,000 dollars of sales into Texas, counting goods and services and counting marketplace sales, can sit in the safe harbor. A Texas resident who sells only through a marketplace still needs a permit. The harbor and the permit answer two different questions.
Form 01-799 is how a remote seller picks one local rate, and the Comptroller's questions page has stated 1.75 percent, with the answer showing on the filing day as the one that wins. A marketplace provider is barred from that single rate.
A short stay of goods inside a marketplace warehouse in Texas, while the seller is still under the safe harbor and the provider's terms say the provider will collect, does not by itself create a permit duty. Cross the harbor and the seller permits and collects, and a taxable entity still has the franchise report on top of that.
Resale paper is the seller's evidence.
Show the next lines
Form 01-339, kept as resale paper, is the seller's evidence that a purchase was for resale. A permit number on its own does not replace that paper. The records stay four years.
If the company takes an item out of resale stock and uses it, tax is due on the fair-market rental value for the time of use, or on the purchase price, and that amount goes on the taxable-purchases line. Picture a spare-parts company we invented, one owner, clearly not a client. A box of bolts leaves the shelf to fix the company's own truck. That use is a taxable purchase, and the software row for parts should not keep pretending the bolts were sold.
Blanket resale paper is allowed only when every purchase from that seller will be resold. A paper offered at a parts counter for a living-room sofa is a paper we question. Resale paper may be issued for resale in the United States or in Mexico. It may not be issued for resale in other countries.
A password is never part of the answer we give, and a password is never something we ask you to type into a form on this site.
What to bring to the call.
Show the next lines
Bring the software row, the sentence the other person used, and the May page you are unsure about. If one of those three is missing, say which one in the form below or on the calendar. The phone number under the page works when a booking grid is a poor fit for a notice that is already close.
The reply names one label. The franchise margin, the sales-tax figure, the software row, and the cash change stay in separate sentences. A single subtracted total that hides the label is the thing we refuse to send.
Name the Texas figure.
Name the page. The reply says which label that page carries.

You will be talking to the Steven Palmieri practice.